Since April 2026, United Therapeutics has been in a holding pattern, posting a small loss of 4.2% while floating around $541.72. The stock also fell short of the S&P 500’s 17.5% gain during that period.
Is there a buying opportunity in United Therapeutics, or does it present a risk to your portfolio? Dive into our full research report to see our analyst team’s opinion, it’s free.
Why Is United Therapeutics Not Exciting?
We don’t have much confidence in United Therapeutics. Here are three reasons why UTHR doesn’t excite us, plus one stock we’d rather own.
1. Revenue Projections Show Stormy Skies Ahead
Forecasted revenues by Wall Street analysts signal a company’s potential. Predictions may not always be accurate, but accelerating growth typically boosts valuation multiples and stock prices while slowing growth does the opposite.
Over the next 12 months, sell-side analysts expect United Therapeutics’s revenue to drop by 3.2%, a decrease from its 14.7% annualized growth for the past five years. This projection is underwhelming and implies its products and services will see some demand headwinds.
2. Shrinking Adjusted Operating Margin
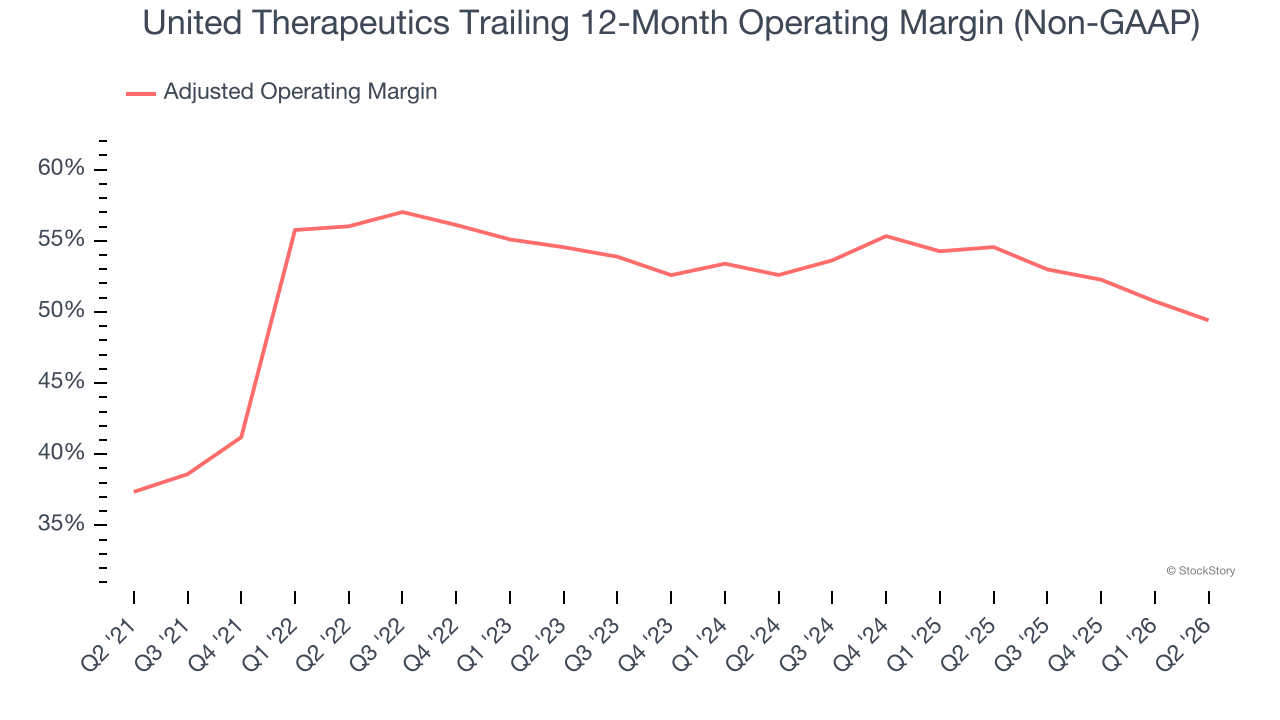
Adjusted operating margin is an important measure of profitability as it shows the portion of revenue left after accounting for all core expenses — everything from the cost of goods sold to advertising and wages. It’s also useful for comparing profitability across companies because it excludes non-recurring expenses, interest on debt, and taxes.
Looking at the trend in its profitability, United Therapeutics’s adjusted operating margin decreased by 6.6 percentage points over the last five years. This raises questions about the company’s expense base because its revenue growth should have given it leverage on its fixed costs, resulting in better economies of scale and profitability. Its adjusted operating margin for the trailing 12 months was 49.4%.
3. Free Cash Flow Margin Dropping
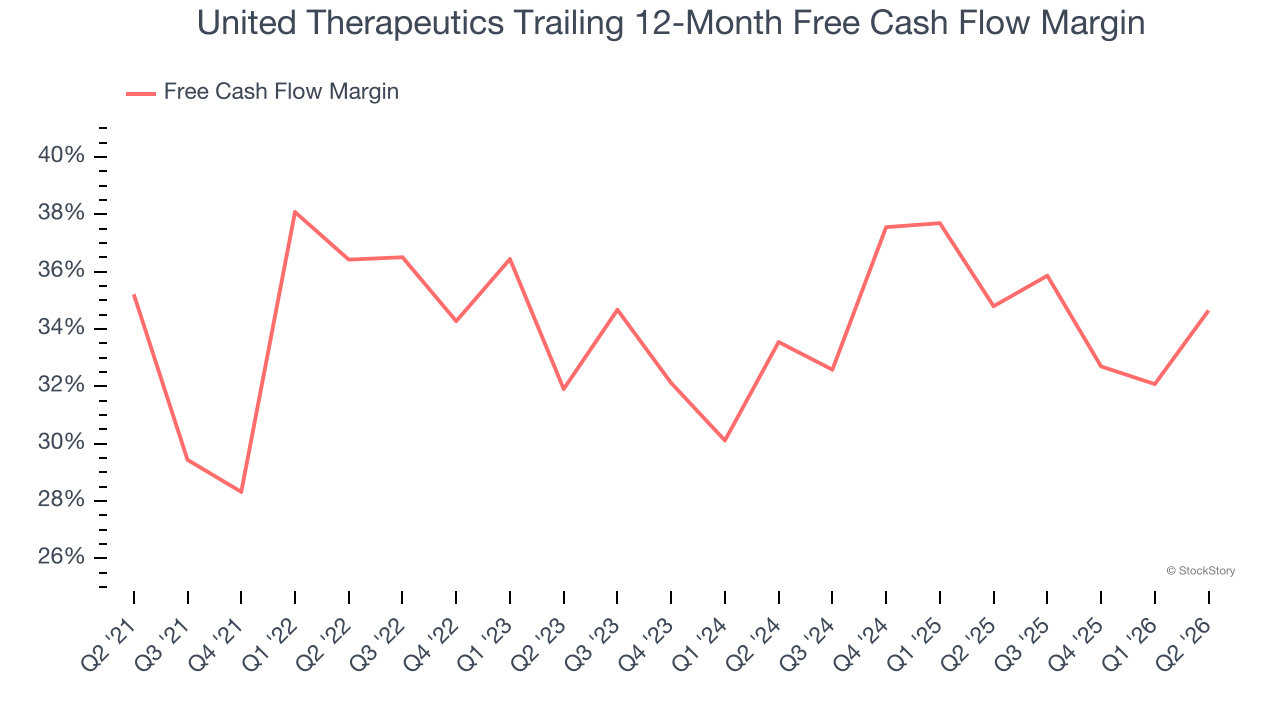
If you’ve followed StockStory for a while, you know we emphasize free cash flow. Why, you ask? We believe that in the end, cash is king, and you can’t use accounting profits to pay the bills.
As you can see below, United Therapeutics’s margin dropped by 1.8 percentage points over the last five years. Continued declines could signal it is in the middle of an investment cycle. United Therapeutics’s free cash flow margin for the trailing 12 months was 34.6%.
Final Judgment
United Therapeutics isn’t a terrible business, but it doesn’t pass our bar. With its shares trailing the market in recent months, the stock trades at 18× forward P/E (or $541.72 per share). While this valuation is fair, the upside isn’t great compared to the potential downside. We’re fairly confident there are better investments elsewhere. We’d recommend looking at one of our all-time favorite software stocks.
High-Quality Stocks for All Market Conditions
ALSO WORTH WATCHING: Top 5 Momentum Stocks. The best time to own a great stock is when the market is finally noticing it. These aren’t just high-quality businesses. Something is happening with them right now. Elite fundamentals meet near-term momentum — both boxes checked at the same time.
Find out which stocks our AI platform is flagging this week. See this week’s Strong Momentum stocks — FREE. Get Our Strong Momentum Stocks for Free HERE.
Stocks that have made our list include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as under-the-radar businesses like the once-micro-cap company Tecnoglass (+1,552% between June 2020 and June 2025). Find your next big winner with StockStory today.